Castelion
Castelion builds low-cost, mass-producible hypersonic strike missiles engineered for industrial-rate output, targeting U.S. Air Force, Navy, and Army requirements.
Background
Castelion was founded in 2022 in Southern California by three former SpaceX engineers: Bryon Hargis (CEO), Sean Pitt (COO), and Andrew Kreitz (CFO).
The trio applied SpaceX-style iterative development and manufacturing philosophy to hypersonic weapons, a domain previously dominated by cost-plus primes with decade-long timelines.
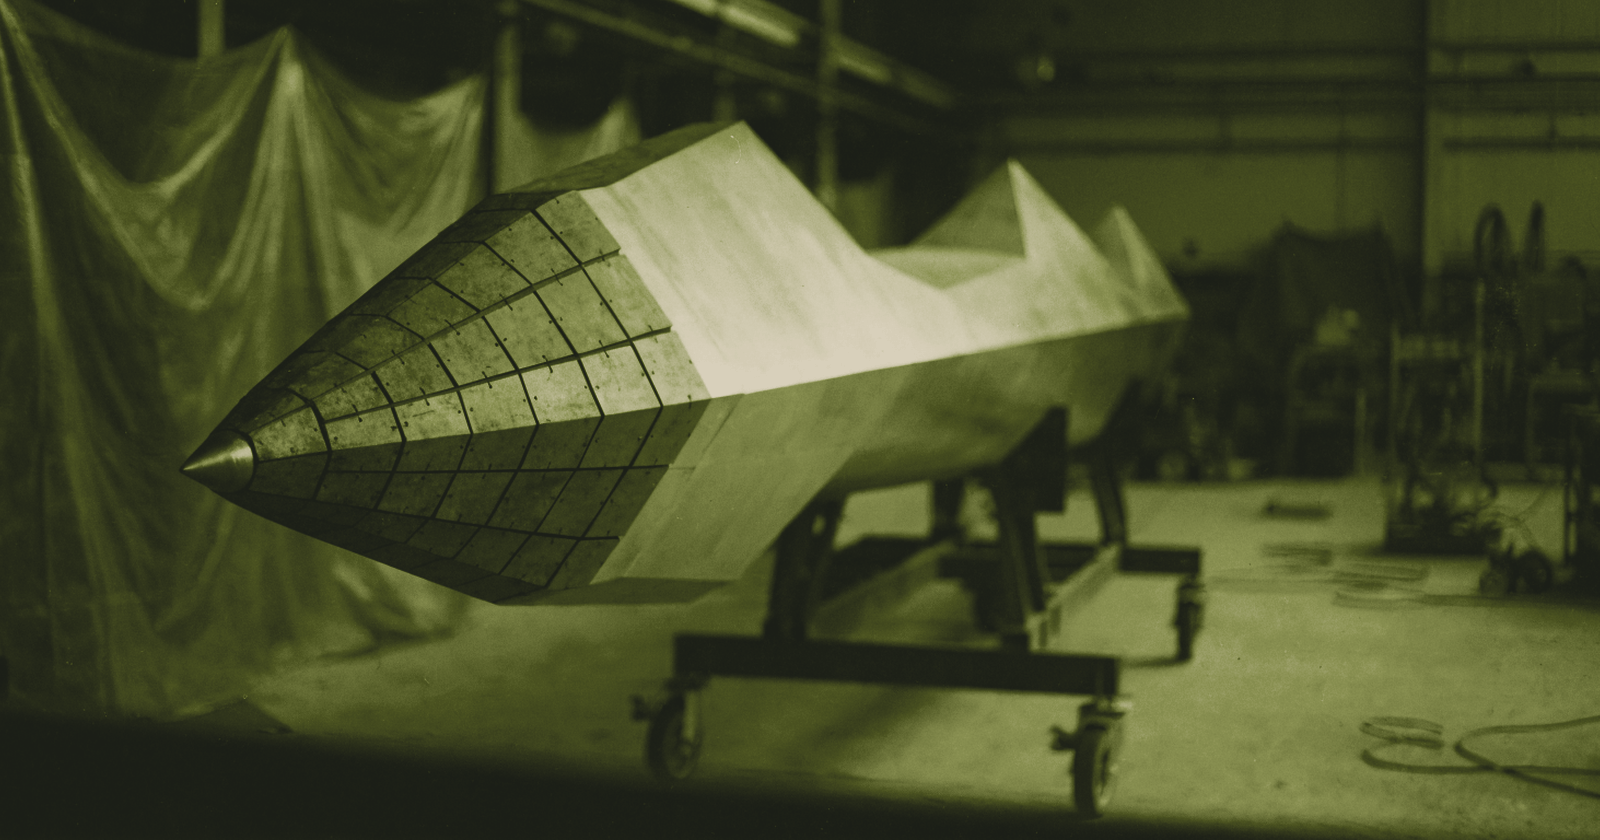
The company's flagship system is Blackbeard, billed as the first U.S. hypersonic weapon explicitly designed for commercial unit cost and continuous flight-test iteration rather than one-off demonstration.
A ground-launch variant, Blackbeard GL, is under development for the U.S. Army's Project HX3. The broader product thesis centers on industrial-rate output — producing hypersonic strike missiles at volumes and price points legacy primes have not demonstrated.
Castelion sells directly to U.S. military services through government contracts and AFRL/NAVAIR grant mechanisms. Headcount was reported at 80–100 employees in early 2025, with LinkedIn estimates placing the team in the 51–200 band as of mid-2026.
Linked records
Wired to the rest of BattlePolicy — the systems it builds in the Lexicon and the contracts it wins in the Procurement Tracker. Every link below is a record in our own datasets.
Financial footing
- $350M Series B (Dec 2025; valuation unconfirmed — "$2.8B" was unsourced)
- Navy Blackbeard ~$49.9M (Feb 2026) + $105M F/A-18 integration (Apr 2026)
- Backers: Lightspeed, Andreessen Horowitz
Castelion raised **$1 billion in Series C in August 2026 at a $13 billion valuation**, a step change from roughly $2.8 billion after the $350 million Series B of December 2025.
The company said the capital funds maximum production rate for Blackbeard plus two further weapon lines.
The earlier ladder: an undisclosed Series A led by Lightspeed with a16z, Lavrock, Cantos, First In, BlueYard and Interlagos; $100 million in combined debt and equity announced January 2025, including $30 million of venture debt from Silicon Valley Bank; then the Series B with Pritzker Group among reported participants.
No revenue has been disclosed. The valuation rests on contracted development work and a Pentagon procurement framework rather than deliveries — Castelion has not yet fielded an operational weapon, which makes $13 billion a bet on a production ramp that has not happened.
Major customers & contracts
Joined live from the Procurement & Contracts Tracker — real award/announcement records.
| Customer | System | Scale / detail | Status |
|---|---|---|---|
| United States | Blackbeard hypersonic (first Navy production order, Castelion) | 50 early operational capability pre-production prototypes and 50 storage and shipping containers | signed |
Further disclosed customers & programs (public reporting):
The U.S. Navy is the primary customer and moved decisively in August 2026, awarding an **$89,997,162 firm-fixed-price order on 25 August** to advance Blackbeard to Early Operational Capability, plus a separate **$23.4 million** order for 50 pre-production prototypes and containers.
Those follow a **$105 million** contract for F/A-18 integration targeting EOC in **2027**, and an earlier ~$49.9 million NAVAIR award reported in February 2026.
The **U.S. Army** funds a parallel surface-launched variant, with $25 million in the FY2026 budget request under Project HX3 for Blackbeard GL. The Air Force Research Laboratory has supported the underlying hypersonic work.
The number that matters most is a Pentagon plan disclosed in May 2026 contemplating procurement of roughly **12,000 Blackbeard missiles** over several years, with a ramp of at least 500 a year once testing completes. The air/surface split is not public, and none of it is a binding bulk buy yet.
Leadership & contact surface
Leadership: Bryon Hargis
Official site: https://www.castelion.com
Competitive position
Against Lockheed Martin and Raytheon — the incumbent hypersonic primes behind LRHW and HAWC — Castelion's edge is unit-cost discipline and iteration speed; its weakness is the absence of a fielded system and the institutional relationships primes leverage for large program-of-record awards. Against Anduril, which competes across autonomous systems and strike with significant DoD backing, Castelion is more narrowly focused on hypersonic propulsion and airframe; Anduril has a broader customer base and larger headcount but has not fielded a hypersonic system.
Against Hermeus, which targets hypersonic aircraft rather than strike missiles, Castelion operates in a more directly weaponized market with earlier military contract traction. Against Northrop Grumman's hypersonic programs, Castelion lacks manufacturing scale but moves faster through flight-test cycles. The market structure remains early-stage: DoD is deliberately seeding multiple vendors to break prime dependency, which benefits Castelion in the near term but creates a crowded field once programs of record consolidate.
Battlefield relevance
Blackbeard has no combat record, and the honest status is integration rather than employment.
The clearest evidence to date is a photograph shown at a Navy future-missiles briefing during the August 2026 Tailhook convention, showing two Blackbeard test articles mounted under the right wing of an **F/A-18E/F Super Hornet**.
That establishes hardware integration has moved past drawings, requirements and ground-launch experimentation onto a carrier-capable aircraft.
What it does not establish — and reporting is explicit about this — is whether Blackbeard has been **fired** from an aircraft.
No captive-carry or live-launch event has been publicly confirmed. Early Operational Capability is targeted for 2027 on the air-launched path.
For a company valued at $13 billion on a hypersonic strike weapon, the distance between "mounted on a Super Hornet" and "launched from one" is the entire remaining risk.
Sources & verification
- https://labusinessjournal.com/la500-2026/technology-2026/la500-2026-andrew-kreitz/
- https://techfundingnews.com/hypersonic-missile-startup-funding-castelion/
- https://www.businesswire.com/news/home/20250129937934/en/Castelion-Announces-100M-Financing
- https://www.caplight.com/company/castelion
- https://www.linkedin.com/posts/space-insider_castelion-a-defense-manufacturer-based-in-activity-7290790898051801089-4_jT
- https://www.cbinsights.com/company/pallas-industries
- https://www.castelion.com/news/series-b/
- https://www.builtinla.com/articles/castelion-raises-350m-series-b-20251208
- https://startupintros.com/orgs/castelion
- https://www.linkedin.com/company/castelion
- https://www.nasdaqprivatemarket.com/company/castelion/
- https://www.facebook.com/forbes/posts/three-year-old-castelion-is-worth-28-billion-after-raising-350-million-to-fund-i/1250713213585333/
- https://equityzen.com/company/pallas4707/
- https://www.castelion.com
- https://www.youtube.com/watch?v=jaXzkKRJOLI
Analyst verdict Pro
Castelion's proposition is cost discipline applied to a category that has resisted it.
Lockheed's LRHW and the HAWC lineage produced exquisite, scarce weapons; Castelion is selling a hypersonic strike missile cheap enough to buy in thousands, and the Pentagon's contemplated 12,000-round framework indicates the customer believes the pitch.
The August 2026 Navy awards are the meaningful validation — $90 million to reach Early Operational Capability and $23.4 million for 50 pre-production rounds is the transition from study money to hardware money, and the F/A-18 photograph confirms physical integration.
Our reservation is the gap between valuation and demonstrated performance. A $13 billion mark on a weapon with no confirmed air launch prices a successful ramp that has not begun; the 500-a-year rate and the 12,000-missile total are contingent on test completion, not contracted.
Watch three things: a confirmed live launch from the Super Hornet, which converts the thesis from plausible to proven; whether the Army's surface-launched HX3 path is funded beyond $25 million; and whether the 12,000-unit framework becomes a binding multi-year buy rather than a planning figure.